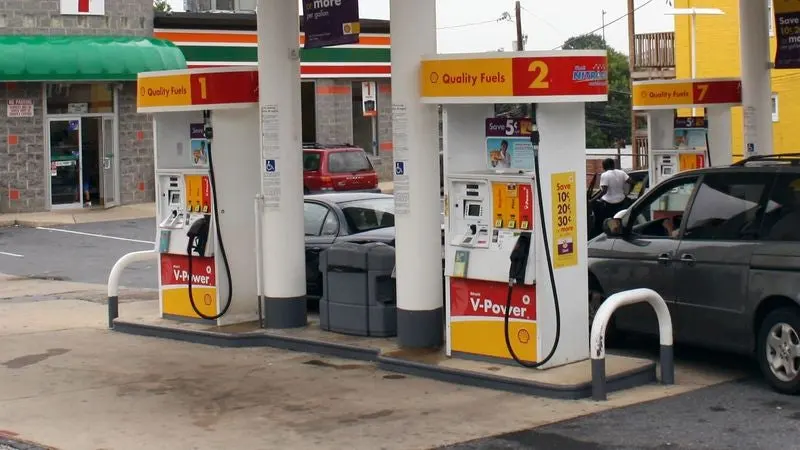

Imagine two gas stations on opposite sides of a road. Each sells an identical product and attracts effectively the exact same consumer base. Holding these factors equal, the natural pull for each station is for each to slightly lower their price so as to undercut their competitor and capture more of the market. Yet, rather than allowing natural competition to lower prices, both stations raise their prices. An outsider might say that the firms must be actively colluding to raise prices and capture higher revenues. Yet neither firm has contacted the other, nor have the stations agreed to fix prices. The pricing software they use has simply learned that in this case, cooperation is more profitable than competition.
This is the rising problem of algorithmic collusion: markets experience higher prices as firms use pricing algorithms that independently avoid undercutting competitors.
Traditionally, economists understand collusion by modelling oligopolic pricing as a supergame, a repeated game in which the same base game is played again and again indefinitely. Day to day, firms can see the prices of their opponents, and for the day after, can reassess their profit-maximizing price and adjust their sales accordingly. Over time, this competition for the market should, left alone, decrease market prices to the marginal cost for each firm, which for the sake of simplicity, we can assume to be identical across oligopolic firms. If both keep lowering their prices, however, they lose profits. When the same firms compete day after day, they may instead recognize that both stand to gain from keeping prices higher. A firm that breaks ranks by cutting its price risks triggering retaliation from its competitor, potentially leaving both worse off. This is the basis of tacit collusion: firms maintain higher prices through their behaviour, without ever explicitly agreeing to do so.
Algorithms can make the process of arriving at a tacit-collusive equilibrium considerably more likely. Unlike human managers, pricing software can monitor competitors' prices continuously and respond almost instantaneously. More importantly, developments in machine learning mean that algorithms no longer simply follow instructions written by their programmers. Through reinforcement learning, they can experiment with different prices, observe the resulting profits and gradually learn which strategies work best, damaging the natural competition of the market.
Calvano et al. sought to model algorithmic pricing using Q-learning, a reinforcement learning algorithm that relies on trial and error, with a duopolistic market like the gas station example as the baseline. Their results were striking, and indicated that under pure trial-and-error conditions, even simple pricing algorithms often learn to choose collusive strategies and maintain prices that are significantly above the non-algorithmic equilibrium. Punishment of non-collusion through undercutting featured prominently in all scenarios in which supracompetitive prices appeared.
The implications are significant. Collusion has traditionally been assumed to require communication, either through explicit agreements or more subtle forms of conscious coordination. Yet with the massive increase in algorithmic price-setting across industries, it is worth considering that increasingly sophisticated pricing systems could make previously-competitive markets more susceptible to outcomes that are not socially optimal. While Calvano’s research is largely theoretical, real-world data analyzing algorithmic pricing in the German petrol market shows that the adoption of pricing software massively increases margins in non-monopolistic markets.
The ease of tacit collusion presents a problem for competition authorities. Traditional competition law, such as the US Sherman Act, typically requires evidence of explicit agreement to establish that unlawful collusion has occurred. If algorithms arrive at tacitly collusive pricing strategies independent of one another, however, identifying an agreement becomes much more difficult, negatively impacting consumers used to competitive markets. Joseph Harrington (2018) explores this problem under US antitrust law, arguing that autonomous algorithmic collusion falls outside the conventional interpretation of unlawful agreements. While the difficulty in establishing evidence of unlawful collusion without an explicit agreement between humans comes from the fact that it is somewhat difficult to read minds, Harrington correctly argues that we can read the mind of a machine to punish algorithmic price-fixing. By observing learning patterns of autonomous agents, it is possible to determine if observed supracompetitive prices rely on the defection punishment framework also noted by Calvano.
It would, however, be misleading to suggest that algorithmic pricing is inherently harmful. Depending on market structure, software can reduce businesses' operating costs or respond more accurately to changes in demand and intensify competition by allowing firms, particularly newer or smaller participants in an established market, to identify opportunities to undercut their rivals.
Algorithmic pricing challenges a fundamental assumption of competition policy: that collusion requires competitors to coordinate. If algorithms can independently learn that higher prices are more profitable when rivals behave similarly, then the distinction between natural competition and tacit cooperation becomes increasingly difficult to establish. Regulators must now confront a market in which firms do not need to agree to collude for consumers to experience the consequences.
Rahul Sundaresan is Deputy Editor-in-Chief of the Consilium and a first-year Economics and Politics student. He writes weekly, focusing mostly on political economy and international economics.